
Local service guide
Website Design in Pittsburgh: Scope, Ownership and Tax
Arrange Website Design in Pittsburgh by asking designers to quote the same pages, customer tasks and handover requirements. Before you sign, establish who will control the finished website, request an itemized tax explanation and agree on accessibility testing. Pennsylvania distinguishes websites transferred to customers from websites developers retain and control, so ownership deserves attention alongside the design fee. [1]
Write a brief around the customer task
Choose the main action you want a customer to complete: call your shop, request an estimate, book an appointment or buy a product. Describe that action before choosing colors or reviewing mockups. Give the designer your current website address, a page list, business hours, contact details and any booking or payment system you want to retain.
Ask for a proposal that names each deliverable. Separate page design, writing, photography, product entry, integrations and migration. Specify who supplies each item and who approves it. Request a launch schedule that identifies your content deadlines, design review dates and the point at which you can test the site.
For a customer visiting your premises, ask the designer to make directions, entrance information and contact options easy to find. For a business serving customers at their locations, provide the actual service area and any booking restrictions. Review those details yourself before launch rather than asking the designer to infer them.
Compare the full proposal cost
Ask each designer to separate the build fee from recurring charges. Request the renewal cost and billing frequency for hosting, software subscriptions, maintenance and support. Ask what happens if you decline the maintenance plan, need another page or change the booking system after launch. Compare proposals using the same scope and the same period of ongoing service.
Pennsylvania's website-development guidance says a website transferred to the customer and its maintenance are taxable. It also treats access to software that lets users build websites as taxable. The department identifies separately stated website hosting fees as nontaxable. Ask the provider to identify the taxable components and explain the calculation before you approve the quote. [1]
Do not assume that a designer's description of the project as custom settles the tax question. The department has a specific website-development section and says it considers the substance of a transaction, including contracts and statements of work. Request an explanation tied to your deliverables and ownership arrangement. [1]
Agree on control and an exit plan
Ask the designer to list who will hold the domain registration, hosting account, website administrator account and software licenses. Put the handover requirements in the contract. Request your own access, an explanation of any export limits and a list of assets or subscriptions that you cannot transfer to another provider.
Pennsylvania describes website development as nontaxable when the developer retains possession and control of the website. That distinction makes control a local purchasing question as well as a handover question. Before choosing that arrangement, ask how you would move your content, retain your domain and keep operating if you ended the relationship. [1]
For a redesign, ask the provider to inventory your existing pages and agree on how customers will reach replacement pages. Confirm that changing the website will preserve the email setup you want to keep. Set a backup and recovery plan, then assign responsibility for testing forms and customer messages after launch.
Make accessibility part of acceptance
The Justice Department states that ADA requirements apply to goods and services public accommodations offer online. Its business guidance identifies barriers such as poor contrast, missing image descriptions, inaccessible forms and mouse-only navigation. Include these checks in the designer's scope and ask which technical accessibility standard they will use. [3]
Ask the designer to demonstrate the main customer task using a keyboard. Review form labels, instructions and error messages. Check that customers can enlarge text and understand required fields without relying on color. These checks follow the department's accessibility guidance; use them as acceptance tasks rather than treating a visual mockup as the finished review. [3]
Request a record of manual checks, automated findings and corrections. The department recommends pairing manual review with automated checkers and cautions against treating a clean report as proof that everything is accessible. Agree on who will handle accessibility problems customers report after launch. [3]
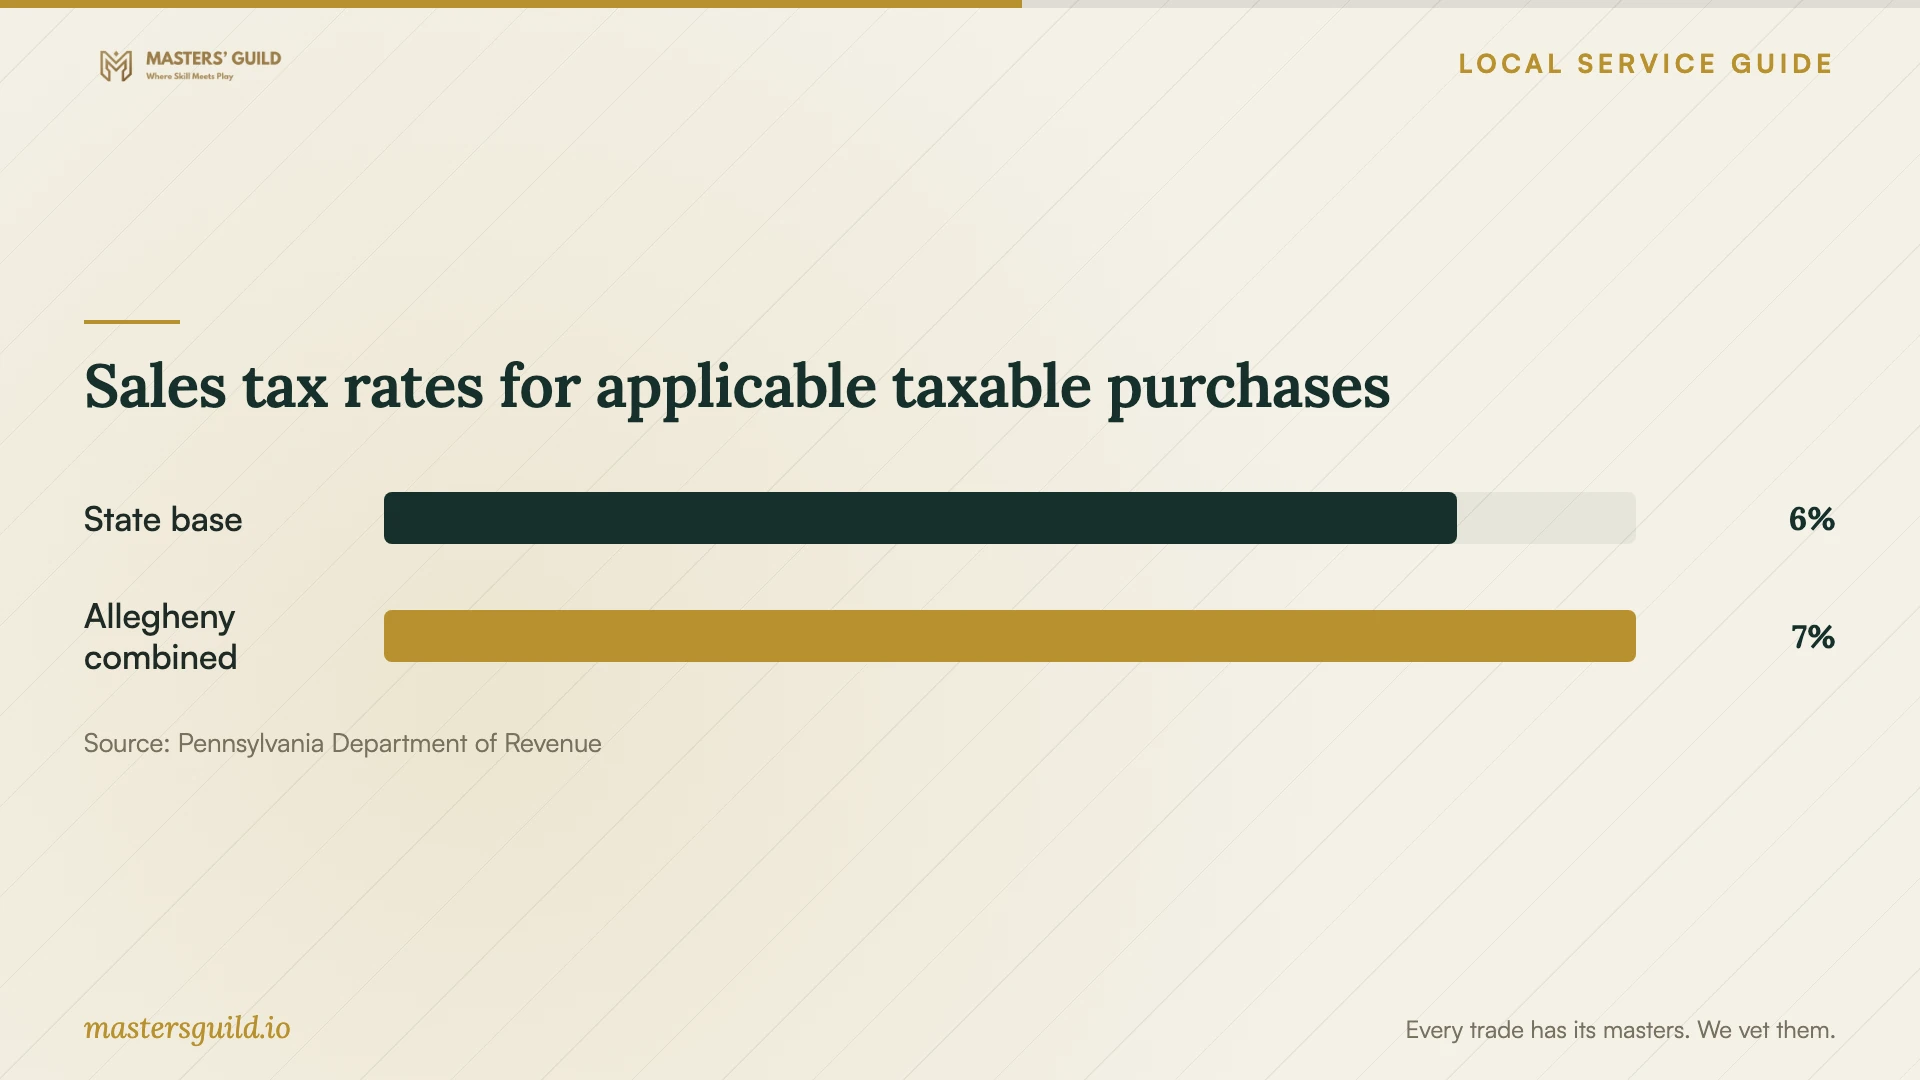
Sales tax rates for applicable taxable purchases
Local details that affect your job
Allegheny County changes the taxable total
Pennsylvania sets a 6 percent state sales tax and adds 1 percent for purchases made in Allegheny County. For a taxable purchase subject to that county rate, the combined rate is 7 percent. Ask your designer to show which charges attract tax and confirm the applicable location treatment, especially when comparing a local provider with an out-of-state provider. [2]
Pennsylvania links website tax to transfer and control
State guidance distinguishes a website transferred to the customer from one the developer retains and controls. It treats the former and its maintenance as taxable, and the latter development arrangement as nontaxable. It also identifies separately stated hosting as nontaxable. Before choosing a managed website package, request both its tax treatment and its exit terms in writing. [1]
Questions to resolve before choosing a proposal
| Proposed arrangement | Decision to make | Ask before signing |
|---|---|---|
| Website transferred to your business | Confirm handover and budget for applicable tax | What accounts and assets will I receive, and which build and maintenance charges are taxable? |
| Developer retains possession and control | Review the exit terms alongside the state's nontaxable development treatment | How can I move my content and domain if I leave? |
| Software-based website builder | Confirm taxable software access and the ongoing subscription commitment | Who holds the subscription, and what can I export? |
| Separately stated website hosting | Keep hosting identifiable when reviewing the invoice | Does the quote list hosting separately from taxable deliverables? |
Your hiring checklist
- Name the main customer action and list the pages needed to support it.
- Assign responsibility for writing, images, product details and approvals.
- Request separate build, recurring, optional and tax charges.
- Record who controls the domain, website accounts and transferable assets.
- Agree on content deadlines, review dates and launch acceptance tasks.
- Ask for keyboard, form and text-enlargement demonstrations.
- Confirm backups, migration arrangements and preservation of business email.
- Document post-launch support and the process for leaving the provider.
Frequently Asked Questions
How much should I budget for the website?
Request written quotes against the same brief. These sources do not establish a Pittsburgh design-price range. Compare the build, content work, subscriptions, support and tax, and ask each provider to price optional features separately.
Does Pennsylvania tax website design?
The Department of Revenue says websites transferred to customers and their maintenance are taxable. It describes development as nontaxable when the developer retains possession and control, and separately stated hosting fees as nontaxable. Ask the provider to explain your arrangement. [1]
Can an automated accessibility report settle acceptance?
Use it alongside manual checks. The Justice Department says a clean automated report does not necessarily mean everything is accessible. Ask the designer to demonstrate keyboard navigation and accessible forms, then document corrections. [3]
What should I receive at handover?
Specify account access, agreed files and content, backup instructions, subscription details and editing guidance. Ask the designer to identify anything you cannot transfer. Require the handover list in the contract so you can review it before final acceptance.
Sources and scope
This guide combines the sources below with practical planning guidance. Figures apply to the stated geography and period; request a written quote for your property.