
Local service guide
Las Vegas tax preparation and accounting
For tax preparation and accounting in Las Vegas, choose a professional who can handle your business records, prepare the required returns and provide the level of IRS support you need. Ask for a written scope that separates bookkeeping cleanup, return preparation and recurring compliance. Nevada does not impose individual state income tax, but business owners should still check their federal and Nevada business obligations. [1] [3]
Choose the work before choosing the accountant
Start with the problem you need to solve. You may need a return prepared from complete records, help reconstructing your books, or ongoing accounting with tax filings. Describe your business activity, how you keep records and any missing months before requesting a quote.
Ask the professional to identify the returns included in the engagement and who will prepare and review them. Discuss owner returns alongside business work so you can see which services each quote covers. If you have income, property or operations outside Nevada, ask the preparer to assess any other-state filing requirements.
Keep tax planning and notice response explicit. Ask whether the quoted fee includes a planning meeting, answers after filing, amendments or help with a tax authority's letter. Request a separate estimate for work outside the agreed scope.
Check credentials and IRS representation
The IRS requires a preparer tax identification number, or PTIN, for compensated federal return preparation. Ask who will sign your return and confirm that person has a PTIN. The IRS explains that preparers differ in education, expertise and representation rights. [3]
Enrolled agents, CPAs and attorneys have unlimited representation rights before the IRS, including audits, collection matters and appeals. Annual Filing Season Program participants have limited rights. Preparers who hold only a PTIN and lack those credentials or program participation have no representation authority for current returns. [3]
Ask a prospective professional about experience with your type of business and the specific issue you face. A credential establishes a qualification; your conversation should establish who will do the work, whether they accept the assignment and how they will communicate with you. [3]
Include Nevada business compliance in the scope
Nevada's lack of individual income tax does not remove its other taxes. The Department of Taxation identifies sales and property taxes and says Commerce Tax applies to businesses whose fiscal-year gross revenue exceeds $4 million. Ask your accountant to assess your business obligations instead of treating a federal return as the complete engagement. [1]
For businesses handling taxable goods, discuss sales and use tax records. Nevada describes consumer use tax as applying to goods used, stored or consumed in the state when sales tax has not been paid, including purchases from out-of-state vendors. Ask who will review those purchases and prepare any required reporting. [2]
The Department publishes monthly sales-tax filing for taxable sales above $10,000 per month, quarterly filing below $10,000 per month, and annual filing when taxable sales were below $1,500 in the previous year. Have the accountant confirm your assigned filing frequency and responsibility for submissions before agreeing to a recurring fee. [2]
Get a quote you can compare
Give each professional the same description of your records and requested work. Ask for separate prices for initial cleanup, return preparation, recurring bookkeeping and additional advice. Request the assumptions behind the quote, such as the number of accounts, transaction volume and condition of your records.
Agree on a document handoff date and a target completion date after the accountant reviews your records. Ask how they will handle missing information and notify you of extra charges. Specify who authorizes filings, arranges payments and keeps copies of completed work.
For ongoing accounting, request clear deliverables: reconciled accounts, financial reports, a list of unresolved items and a calendar of assigned filings. Choose a secure document-sharing method and identify your main contact before sending financial or identity records.
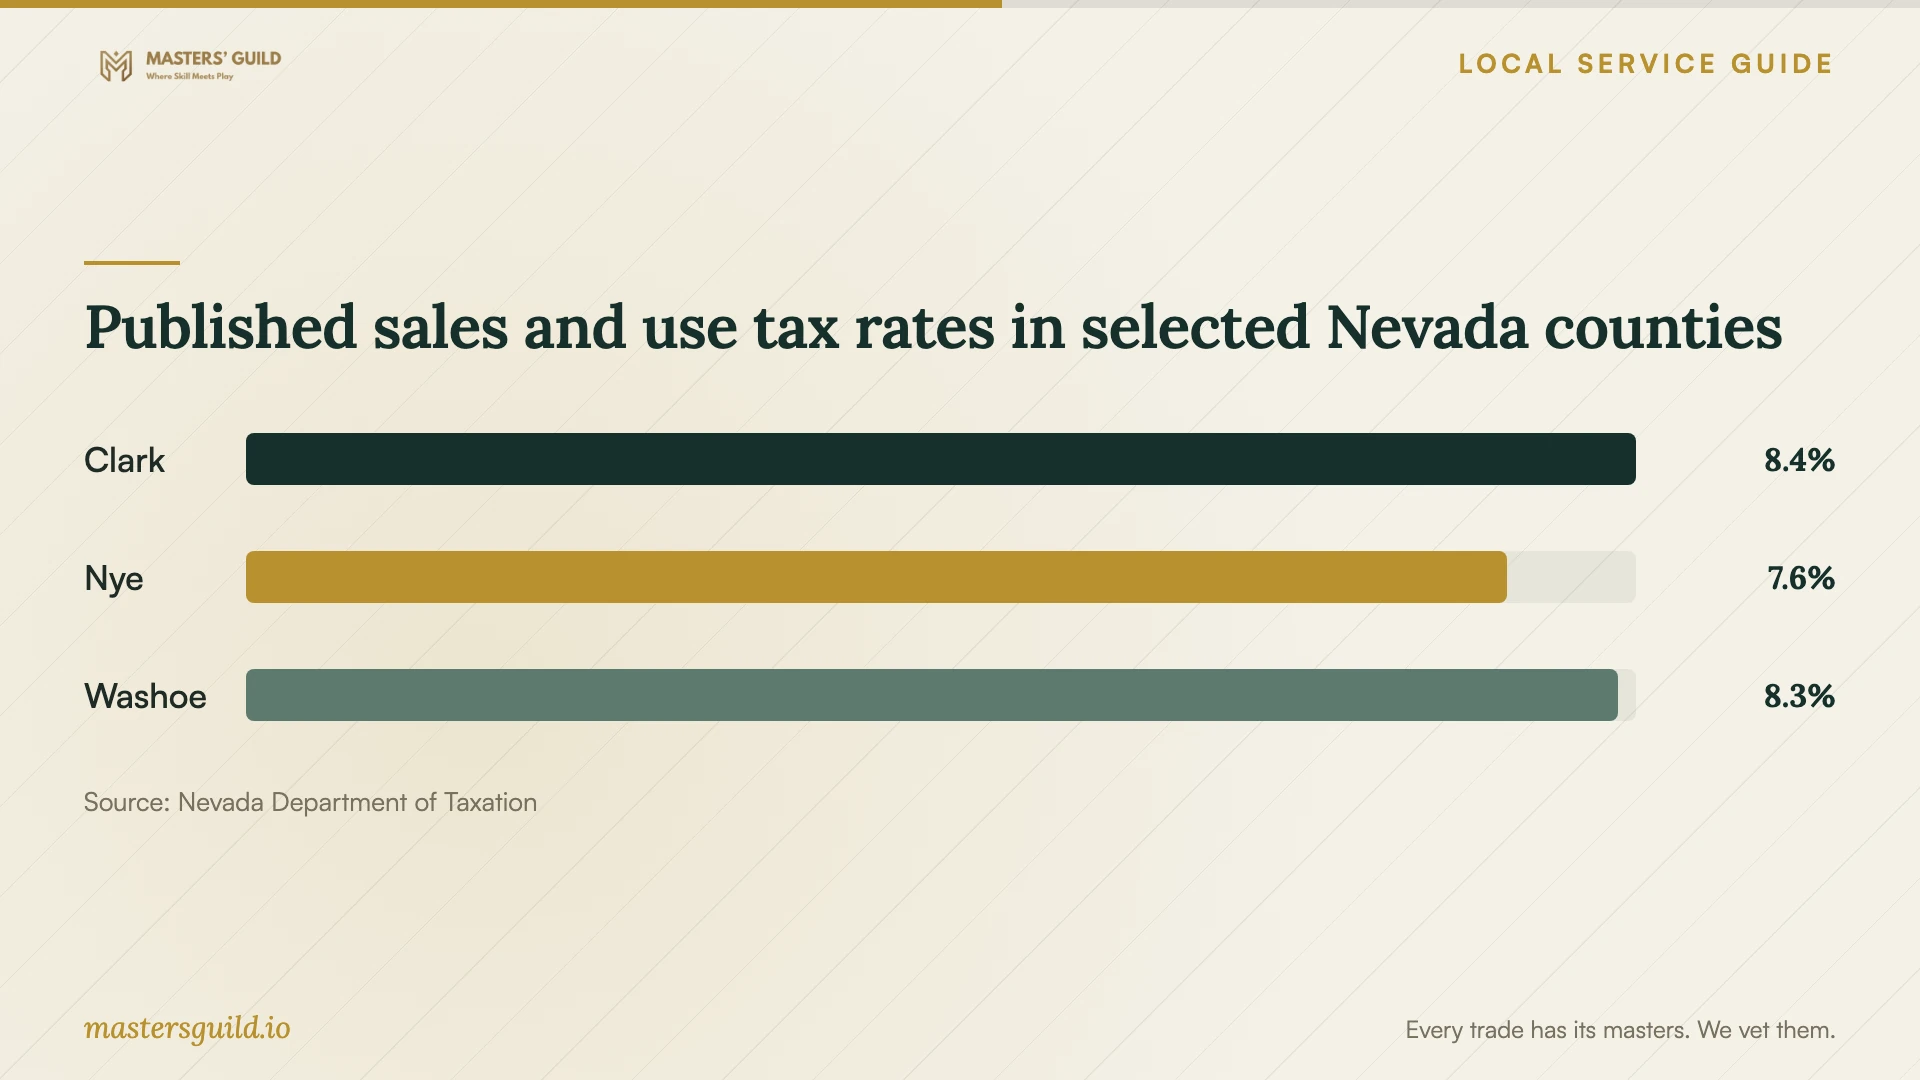
Published sales and use tax rates in selected Nevada counties
Local details that affect your job
Clark County sales-tax work needs a defined owner
Nevada lists Clark County's sales and use tax rate as 8.375%, effective January 1, 2020. If your business handles taxable transactions, ask the accountant to check transaction locations and reporting periods. Agree whether you or the accountant will reconcile collected tax with sales records and submit returns. [2]
A remote CPA may qualify through practice privileges
The Nevada State Board of Accountancy allows qualifying out-of-state CPAs and firms to work under practice privileges without obtaining a Nevada license or permit. If a remote CPA does not appear as Nevada-licensed, ask for their principal licensing state and verify that license rather than assuming they cannot serve your business. [4]
UNLV's free program requires a separate eligibility check
UNLV's ended January 20, 2026 VITA listing offered free preparation for qualifying taxpayers with 2025 income of $67,000 or less. It excluded state returns and Form 1040-NR and imposed scope limits. Treat it as a prior-season option to investigate for your individual return, not confirmation of business-return coverage or 2027 availability. Confirm current eligibility and scope with UNLV VITA before relying on it. [5]
Match the engagement to your immediate need
| Your situation | Engagement to discuss | Question to settle |
|---|---|---|
| Complete books and a return to prepare | Return preparation with a paid preparer who has a PTIN | Which business and owner returns does the fee include? |
| Missing records or unreconciled accounts | Bookkeeping cleanup followed by preparation | What must you supply before the preparer can complete the work? |
| IRS audit, collection issue or appeal | An enrolled agent, CPA or attorney with unlimited representation rights | Will that professional accept representation, and what will it cost? |
| Taxable goods sales or untaxed business purchases | Sales and use tax review alongside bookkeeping | Who checks transactions, reconciles tax and submits required returns? |
| Considering an out-of-state CPA | Credential verification and a discussion of Nevada practice privileges | Where does the CPA hold a valid license? |
Your hiring checklist
- Describe your business activity, ownership and requested services.
- Gather prior returns, tax notices and a list of unresolved accounting questions.
- Prepare bank and credit-card statements, bookkeeping exports and supporting receipts.
- List missing records and accounts that need reconciliation.
- Ask who prepares, reviews and signs the returns.
- Request a written scope, fee assumptions and approval process for extra work.
- Agree on document delivery, completion targets and responsibility for filings and payments.
Frequently Asked Questions
Does Nevada's lack of individual income tax mean my business needs no tax preparation?
No. Nevada does not impose individual state income tax, but it has other taxes, including sales tax and Commerce Tax for businesses above the stated revenue threshold. Ask the preparer to identify the federal and state work your engagement needs. [1]
Do I need a CPA to prepare a federal return?
The IRS authorizes professionals with a PTIN to prepare federal returns for compensation. CPAs, enrolled agents and attorneys also have unlimited IRS representation rights. Choose based on the work and support you need, and ask about relevant experience. [3]
How much should I budget?
Request a quote after the accountant reviews your records and filing needs. Compare cleanup, preparation and recurring services as separate items. Ask what triggers extra charges and whether the quote includes questions after filing, amendments or notice response.
Can UNLV VITA handle my return for free?
Check current availability and eligibility with UNLV VITA. Its ended 2026 listing applied to qualifying taxpayers with 2025 income of $67,000 or less, excluded state returns and Form 1040-NR, and required a scope review. That listing does not confirm coverage for your business or a future season. [5]
Sources and scope
This guide combines the sources below with practical planning guidance. Figures apply to the stated geography and period; request a written quote for your property.