Local service guide
Tax preparation and accounting in Houston
Tax preparation for a Houston small business starts with a written scope covering your federal return, bookkeeping cleanup and applicable Texas entity reports. Identify the person doing the work, check their credentials and agree on fees before sharing records. For an IRS audit, collection matter or appeal, seek an enrolled agent, CPA or attorney with relevant experience. The IRS gives these professionals unlimited representation rights; preparers with only a PTIN have no representation authority for current returns. [5]
Choose a professional for your specific work
Describe your business structure, tax years, rental activity, employees, transactions outside Texas and any notices you have received. Separate one-time return preparation from ongoing accounting in your request. Ask each candidate which tasks they will handle and which would require another professional.
The IRS distinguishes permission to prepare returns from authority to represent clients. Enrolled agents, CPAs and attorneys have unlimited representation rights for audits, payment and collection matters, and appeals. Annual Filing Season Program participants have limited rights for returns they prepared and signed. Preparers who hold only a PTIN, without those credentials or program participation, cannot represent clients on current returns. [5]
Ask about experience with your entity type and who would respond to a notice after filing. For a CPA engagement, obtain the individual's name and the firm's name. The Texas State Board of Public Accountancy offers separate searches for individual licensees and firms, with status and expiration information in the results. Review both records before agreeing to the engagement. [4]
Include Texas reporting in the engagement
Ask the accountant to identify your Texas franchise reporting obligations alongside the federal return. Texas imposes franchise tax on taxable entities formed or organized in the state or doing business there. The Comptroller sets the annual franchise report deadline at May 15, with a move to the next business day when May 15 falls on a weekend or holiday. [3]
For the 2026 report year, entities with annualized total revenue at or below $2.65 million do not need a No Tax Due Report. They generally still must file a Public Information Report or Ownership Information Report. The Comptroller describes separate treatment for passive entities and qualifying new veteran-owned businesses. Have your accountant identify your classification and name the required reports in the engagement letter. [2]
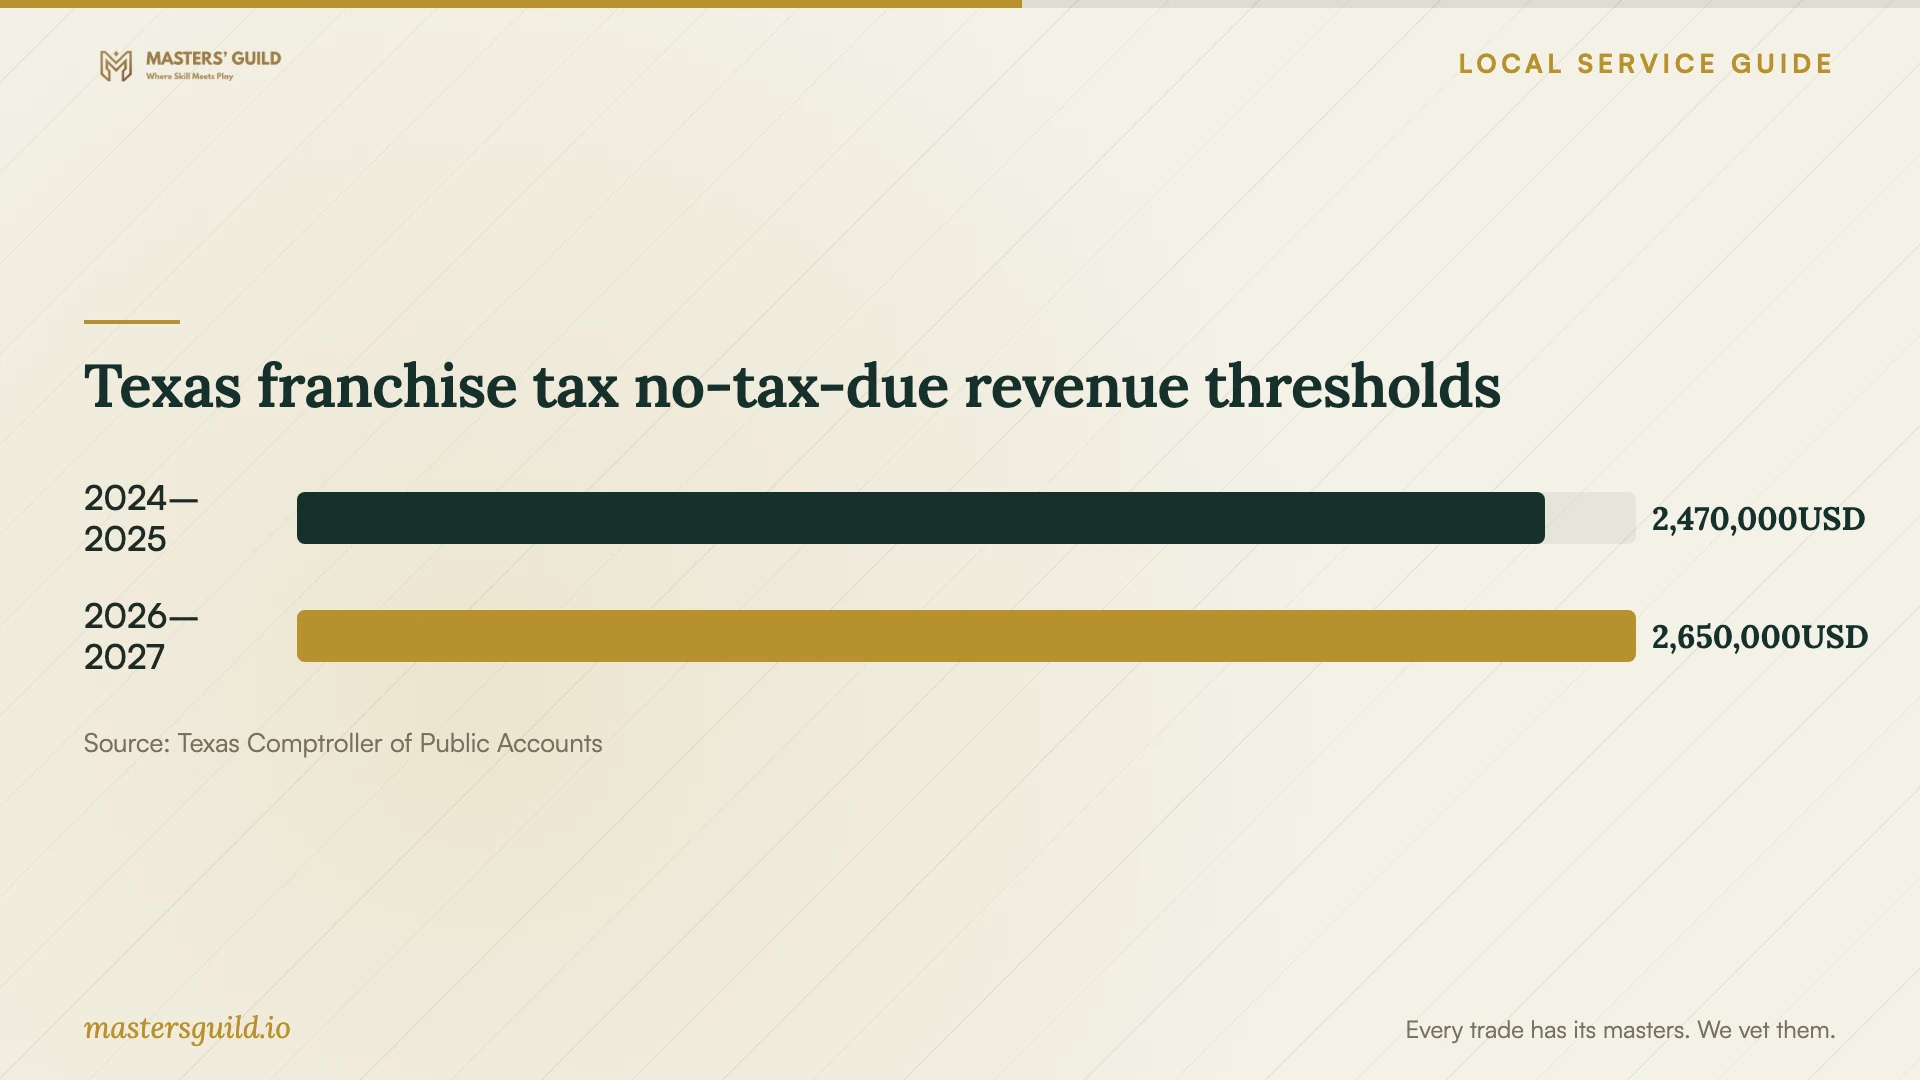
For catch-up work, specify each report year. The Comptroller publishes a $2.47 million no-tax-due threshold for 2024 and 2025 and $2.65 million for 2026 and 2027. Ask the accountant to apply the requirements for each year and provide copies of submitted reports and filing confirmations. [3]
Compare workload-specific quotes
Give each candidate the same records summary and request a written proposal. Separate federal preparation, Texas reporting, bookkeeping cleanup and recurring accounting. Ask whether each charge covers a fixed scope or time spent, which records you must supply and what would trigger an additional fee.
For monthly accounting, name the accounts to reconcile and the reports you want. Specify responsibility for payroll or sales-tax work if you need those services. Agree on how you will approve corrections, access your records and transfer them if you change firms. For a one-time return, set a document deadline and a review meeting.
Obtain quotes for your actual workload before setting a service budget. The Texas revenue thresholds shown in the chart concern franchise reporting; they do not measure preparation or bookkeeping fees. Ask candidates to price notice assistance and prior-year corrections as separate tasks when needed. [3]
Prepare records and agree on delivery
Gather prior returns, complete tax notices, income forms, bank and credit-card statements, and your bookkeeping file. List missing records and transactions you cannot classify. Ask which entity documents, payroll summaries, asset records and ownership details the accountant needs before you send them.
Agree on a secure document exchange method and identify who can access your files. Have the preparer explain unresolved questions before you approve the return. Request final copies and filing confirmations, and keep them with your engagement letter and supporting records.
Texas franchise tax no-tax-due revenue thresholds
Local details that affect your job
Check Harris County free-help restrictions
Harris County Public Library lists AARP Tax Aide at selected branches. Its exclusions include married filing separately, self-employment with a business loss, state income tax returns, rental-property income other than oil and gas leases, and digital assets. If you want assistance with your personal return, describe those activities before choosing this option. Confirm available sessions and whether volunteers can handle your return before traveling. [1]
Confirm BakerRipley access and eligibility
The library lists BakerRipley assistance at Katy and North Channel branches, including personal return preparation and ITIN applications and renewals. Its listing describes walk-in service without appointments and eligibility for families and individuals earning up to $58,000. Confirm current dates, eligibility and return scope with the program before visiting. Ask about business entity returns as a separate question rather than assuming the personal-return service covers them. [1]
Bring Texas franchise notices to the consultation
In its July/August 2026 notice guidance, the Texas Comptroller connects Form 05-211 with unmet 2026 franchise filing requirements and Form 05-213 with unmet 2025 requirements. If you received one of those notices, send the accountant the complete document and identify its report year. Request a plan covering the missing filings, any amounts due and account-status follow-up alongside your next federal return. [3]
Match the engagement to your situation
| Your situation | What to request | Check before agreeing |
|---|---|---|
| Personal return with possible free-help eligibility | Confirm a Harris County library tax session and return scope | AARP Tax Aide excludes business losses, most rental income and digital assets |
| Business return and Texas entity reporting | Federal preparation plus identification of applicable franchise reports | For 2026, revenue at or below $2.65 million generally still leaves PIR or OIR requirements |
| IRS audit, collection issue or appeal | An enrolled agent, CPA or attorney with relevant experience | These credentials carry unlimited IRS representation rights |
| Monthly bookkeeping and year-end preparation | A proposal naming reconciliations, reports and preparation responsibilities | Agree on deliverables, access to records and cleanup charges |
| Texas franchise notice or missing prior-year reports | Notice review and a correction plan for each report year | For July/August 2026 notices, the Comptroller links 05-211 to 2026 requirements and 05-213 to 2025 requirements |
Your hiring checklist
- Write one brief naming your business structure, tax years and requested services.
- Identify the preparer and ask them to confirm their credentials and PTIN.
- Discuss experience with your entity type, notices, rental activity or digital assets.
- Request a list of applicable Texas reports and responsibility for submitting each.
- Compare proposals with separate fees for preparation, cleanup and recurring accounting.
- Agree on document delivery, review dates, approval of extra charges and post-filing support.
- Keep final returns, submitted reports and filing confirmations with your records.
Frequently Asked Questions
Does a paid tax preparer have to be a CPA?
No. The IRS requires paid federal return preparers to have a PTIN. CPAs, enrolled agents and attorneys have professional credentials and unlimited IRS representation rights. Ask about training, relevant experience and who would help if you receive a notice. [5]
Can my business skip Texas reporting if it owes no franchise tax?
Check your entity's requirements. For 2026, entities at or below the $2.65 million annualized revenue threshold generally must file a Public Information Report or Ownership Information Report despite having no No Tax Due Report requirement. Ask your accountant to confirm the classification and any applicable exceptions. [2]
Can library tax assistance handle a rental or business-loss return?
HCPL lists self-employment with a business loss and rental-property income other than oil and gas leases among its AARP Tax Aide exclusions. Describe your return before arranging a visit. Seek a preparer with relevant experience if the program cannot handle your work. [1]
How should I compare accounting quotes?
Give each candidate the same records summary and requested deliverables. Request separate fees for return preparation, Texas reporting, cleanup and recurring accounting. Agree on what would change the price and whether the engagement includes notice assistance.
Sources and scope
This guide combines the sources below with practical planning guidance. Figures apply to the stated geography and period; request a written quote for your property.