Local service guide
Tax Preparation and Accounting in Henderson, NV
Arrange Tax Preparation and Accounting in Henderson by separating annual return preparation from bookkeeping, payroll, and Nevada tax filings before you compare quotes. Ask who will prepare your returns, confirm their PTIN, and choose a CPA, enrolled agent, or attorney if you need representation for IRS audits, collections, or appeals. These credentials carry unlimited IRS representation rights. [5]
Choose credentials for the work you need
Confirm the credentials of the person who will handle your account. The IRS requires paid federal return preparers to have a preparer tax identification number, or PTIN. CPAs, enrolled agents, and attorneys have unlimited representation rights before the IRS, including audits, payment and collection matters, and appeals. [5]
Ask about experience with your entity type and the work you want to assign. A CPA may offer accounting services beyond tax preparation; the IRS notes that some CPAs specialize in tax preparation and planning. Request a concrete explanation of who handles bookkeeping, who reviews the return, and who answers questions after filing. [5]
For a Nevada CPA or CPA firm, use the Nevada State Board of Accountancy's license search and public-information process. The Board accepts requests for public information about licensed CPAs and registered firms. Its policy distinguishes confidential complaint investigations from public disciplinary records, so avoid treating a lack of accessible complaints as proof of a clean history. [4]
Define the engagement before comparing fees
Request separate scope lines for annual tax returns, bookkeeping cleanup, ongoing bookkeeping, payroll, Nevada filings, and tax planning. Specify the business entities and accounting periods involved. Ask the provider to identify work they will exclude and the circumstances that would require a revised quote.
For bookkeeping, agree on bank and credit-card reconciliations, transaction categorization, owner transactions, and the reports you will receive. For payroll, name the person responsible for processing wages, reconciling payroll records, filing returns, and authorizing payments. Put your own document and approval responsibilities in the engagement.
Compare fees only after each provider has reviewed the same description of your records. Ask whether cleanup, amended returns, additional entities, notice responses, and representation require separate fees. Agree on a target completion date and the documents the accountant needs before committing to it.
Include Nevada employer filings in payroll discussions
Nevada imposes Modified Business Tax on employers subject to its Unemployment Compensation Law, with listed exceptions. The Department of Taxation describes the wage base as total gross wages less employer-paid employee health care benefits. General businesses file quarterly returns. [2]
The Department lists a 1.17% general-business rate effective July 1, 2023, with the first $50,000 of quarterly wages remaining non-taxable. Covered employers must file even when no tax is due. Ask the accountant to confirm your employer category and reconcile wage and health-benefit figures before filing. [2]
Review sales activity and Nevada gross revenue
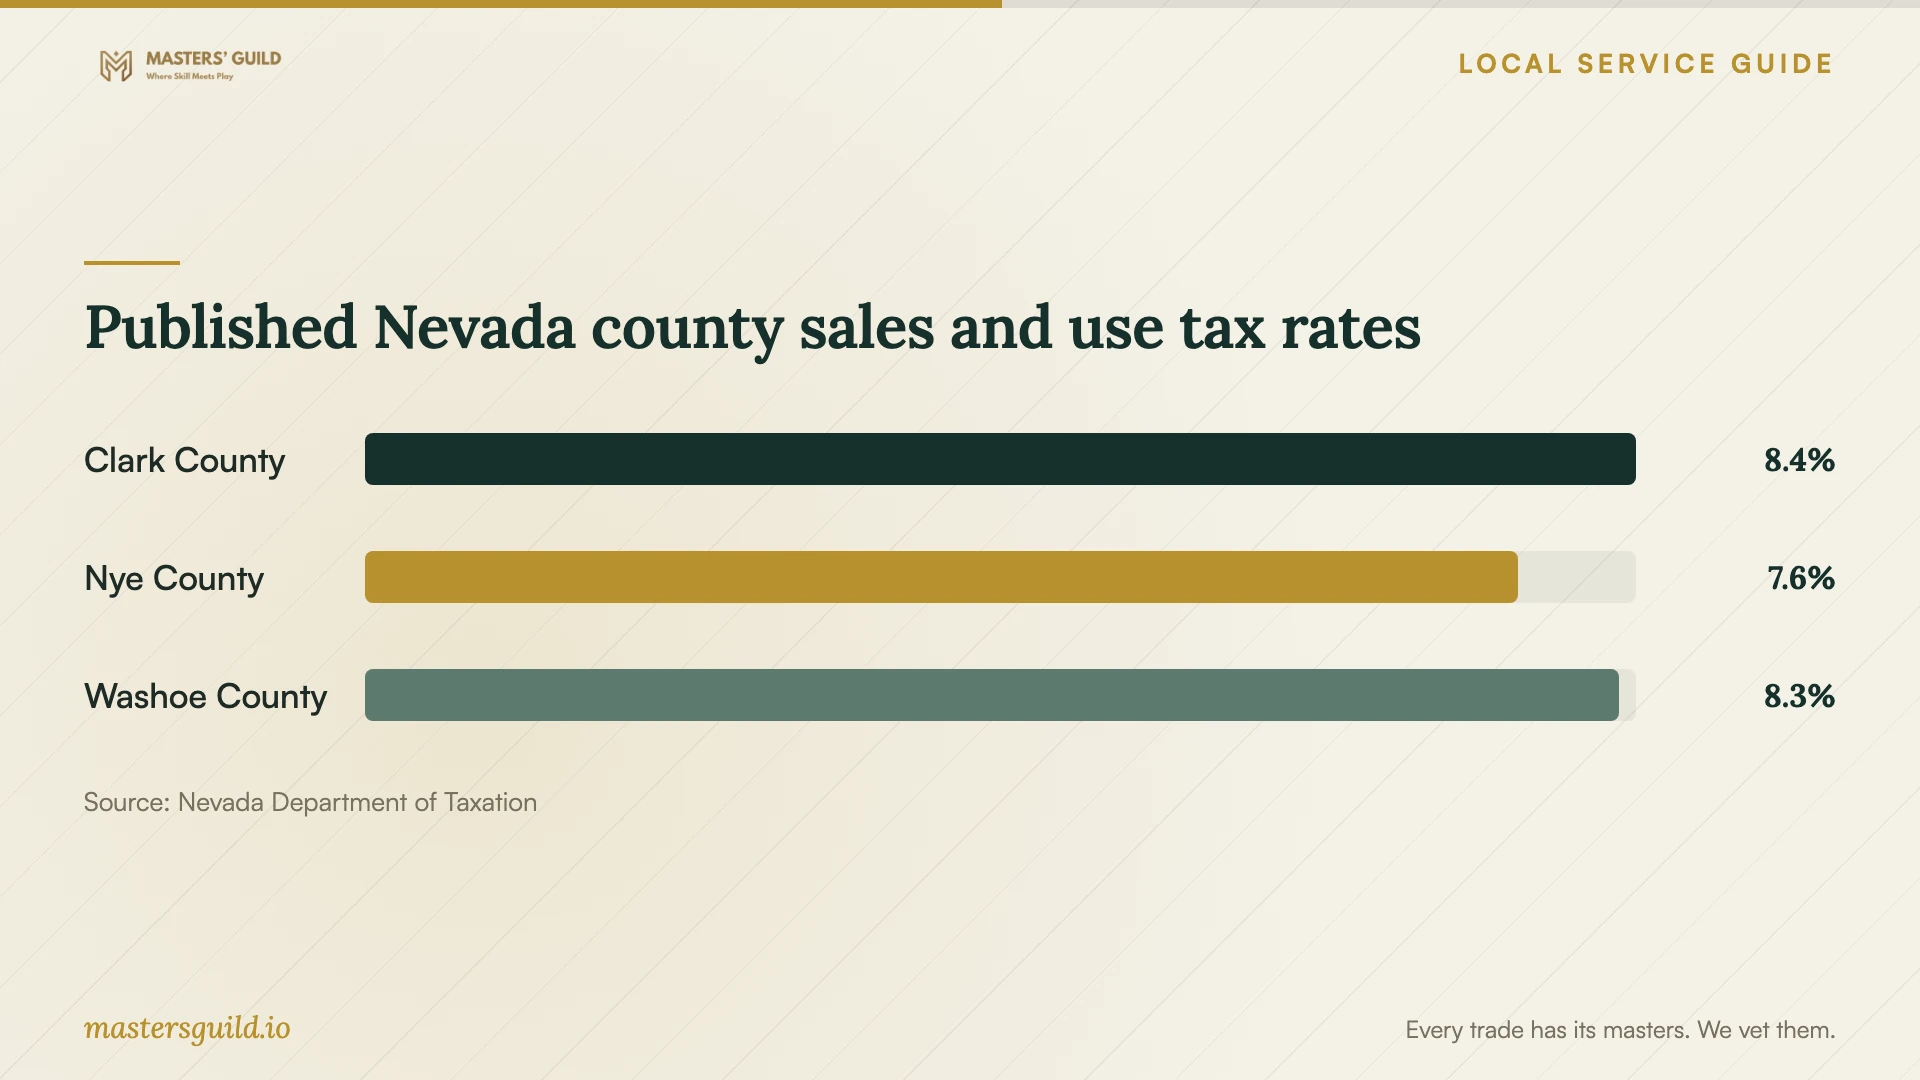
For sales and use tax work, ask the accountant to review transaction locations and applicable rates rather than assigning one rate to all sales. Nevada's published county rates include 8.375% for Clark County, 7.60% for Nye County, and 8.265% for Washoe County. Give the accountant a sales export with enough location detail to assess your activity. [1]
Commerce Tax requires a separate revenue review. Nevada states that business entities with Nevada gross revenue above $4 million during the taxable year must file, subject to applicable exemptions. Businesses at or below that amount generally have no filing requirement. The Department also instructs businesses closing a Commerce Tax account to file a final return. [3]
If you operate several entities, ask for an entity-by-entity review. Nevada does not allow a consolidated Commerce Tax return. The Department also treats rental income as business activity for this tax, so a landlord should have the accountant assess revenue and filing requirements rather than assume rental income falls outside the rules. [3]
Prepare a useful handoff
Gather prior returns, current accounting reports, bank and card statements, payroll reports, asset purchases, loan statements, and tax notices. Tell the accountant which accounts remain unreconciled and which transactions need explanation. For rentals, organize income and expenses by property.
Agree on a secure document-transfer method, review dates, and a contact for questions. Before filing, request a review of material changes from the prior year and confirmation of which returns the provider will submit. After filing, retain the completed returns, submission confirmations, and payment instructions with your business records.
Published Nevada county sales and use tax rates
Local details that affect your job
Nevada payroll support must address zero-tax quarters
For your Henderson business, ask whether the payroll engagement includes Nevada Modified Business Tax returns. The state's general-business rules require quarterly filing even when no tax is due. Put responsibility for those returns in writing instead of assuming the payroll processor or annual tax preparer handles them. [2]
Coordinate Commerce Tax with payroll accounting
Nevada allows an eligible business that pays both Commerce Tax and Modified Business Tax a non-refundable MBT credit equal to 50% of Commerce Tax paid. The credit applies within the four calendar quarters following the Commerce Tax year-end. If different providers handle these taxes, assign responsibility for sharing payment records and tracking the credit before it expires. [3]
Match the engagement to your next task
| Your situation | Work to request | Point to confirm |
|---|---|---|
| Annual return preparation | A defined return-preparation engagement | The paid federal preparer has a PTIN |
| IRS audit, collection issue, or appeal | Representation by a CPA, enrolled agent, or attorney | The professional accepts the matter and explains the separate fee |
| Employees on payroll | Payroll reconciliation and Nevada MBT review | Who files quarterly returns, including zero-tax returns |
| Nevada gross revenue approaching $4 million | Commerce Tax threshold and exemption review | Which entities have a filing requirement |
| Unreconciled business accounts | Bookkeeping cleanup before return preparation | The periods, accounts, and deliverables included |
Your hiring checklist
- List each business entity, rental activity, and accounting period in the requested scope.
- Ask the named preparer to confirm their PTIN and professional credentials.
- Describe unreconciled accounts and request a separate cleanup quote.
- Assign responsibility for payroll processing, returns, and payment approvals.
- Ask the accountant to assess Nevada sales, payroll, and Commerce Tax obligations.
- Confirm fees for notices, amendments, and representation.
- Agree on document delivery, review dates, and the records you will receive.
Frequently Asked Questions
Do I need a CPA to prepare my federal return?
The IRS permits professionals with a PTIN to prepare federal returns for compensation. A CPA is one option. Choose based on the work and support you need; CPAs, enrolled agents, and attorneys have unlimited IRS representation rights. [5]
Does a zero Modified Business Tax bill mean I can skip the return?
No. Nevada requires covered general-business employers to file quarterly MBT returns regardless of tax due. Ask your provider to confirm whether your business falls under those rules or an exception. [2]
Does owning a rental property create a Commerce Tax filing requirement?
Ownership alone does not establish that you must file. Nevada treats rent as business activity for Commerce Tax, but generally requires filing when Nevada gross revenue exceeds $4 million during the taxable year. Ask for a review of your revenue and applicable exemptions. [3]
Sources and scope
This guide combines the sources below with practical planning guidance. Figures apply to the stated geography and period; request a written quote for your property.