Local service guide
Tax Preparation and Accounting in Fargo, ND
For Tax Preparation and accounting in Fargo, choose a professional who can explain your business and personal filing needs, assess Minnesota activity, and quote the work you need. Compare proposals using the same records and deliverables. Minnesota does not provide reciprocity for business income, so disclose cross-border work and sales before accepting a proposal. [1]
Choose between annual preparation and ongoing accounting
Start by describing your ownership, entity type, employees, accounting software, and work locations. Decide whether you want annual return preparation, help reconciling records, or accounting support during the year. Give each candidate the same description so you can compare their proposed work.
For ongoing accounting, discuss the reports you want to review and how you will use them. You might need a monthly income statement, a balance sheet, or help understanding owner withdrawals and loan balances. Agree on a review schedule and identify the person who will answer questions.
Describe any gaps in your records before requesting a price. Tell the accountant about missing statements, unreconciled accounts, and personal spending in business accounts. Ask for a fixed fee with stated assumptions or an hourly estimate with an approval point for additional work.
Explain Minnesota activity before hiring
Minnesota’s reciprocity guidance covers qualifying personal-service income, including wages, salaries, tips, and commissions. To qualify, you must reside in one reciprocity state, receive personal-service income from the other, and return to your home state at least once a month during the year. [1]
Minnesota does not provide reciprocity for business income. Its guidance addresses sole proprietors, independent contractors, partners, and shareholders. It also describes a limited exclusion for qualifying compensation from personal or professional services you provide, with restrictions involving employees and sales of goods. Have the preparer assess your activities before assuming an exemption. [1]
Prepare a breakdown of wages, customer receipts, rental income, and property sales by state. Include work locations and any move dates. If you receive both wages and ownership income from a business, have the accountant explain the treatment of each and identify the proposed state filings.
Check credentials and evaluate the proposal
The North Dakota State Board of Accountancy provides a verification entry point for searching CPA licensees and firms. Use it when a candidate offers CPA services, and match the names to the person and firm you plan to engage. [2]
Discuss experience with your entity type and the filings your accountant proposes. Ask who prepares and reviews the work, how you will receive answers during the year, and what help you can expect after a tax notice. Request an explanation of their approach to your situation without seeking another client’s confidential information.
Read the engagement terms for exclusions, payment timing, and extra-work approval. Compare total fees against the listed deliverables. Agree on your document deadline and the accountant’s target completion date, and explain any unresolved records that could affect that schedule.
Plan sales-tax work and personal estimated payments
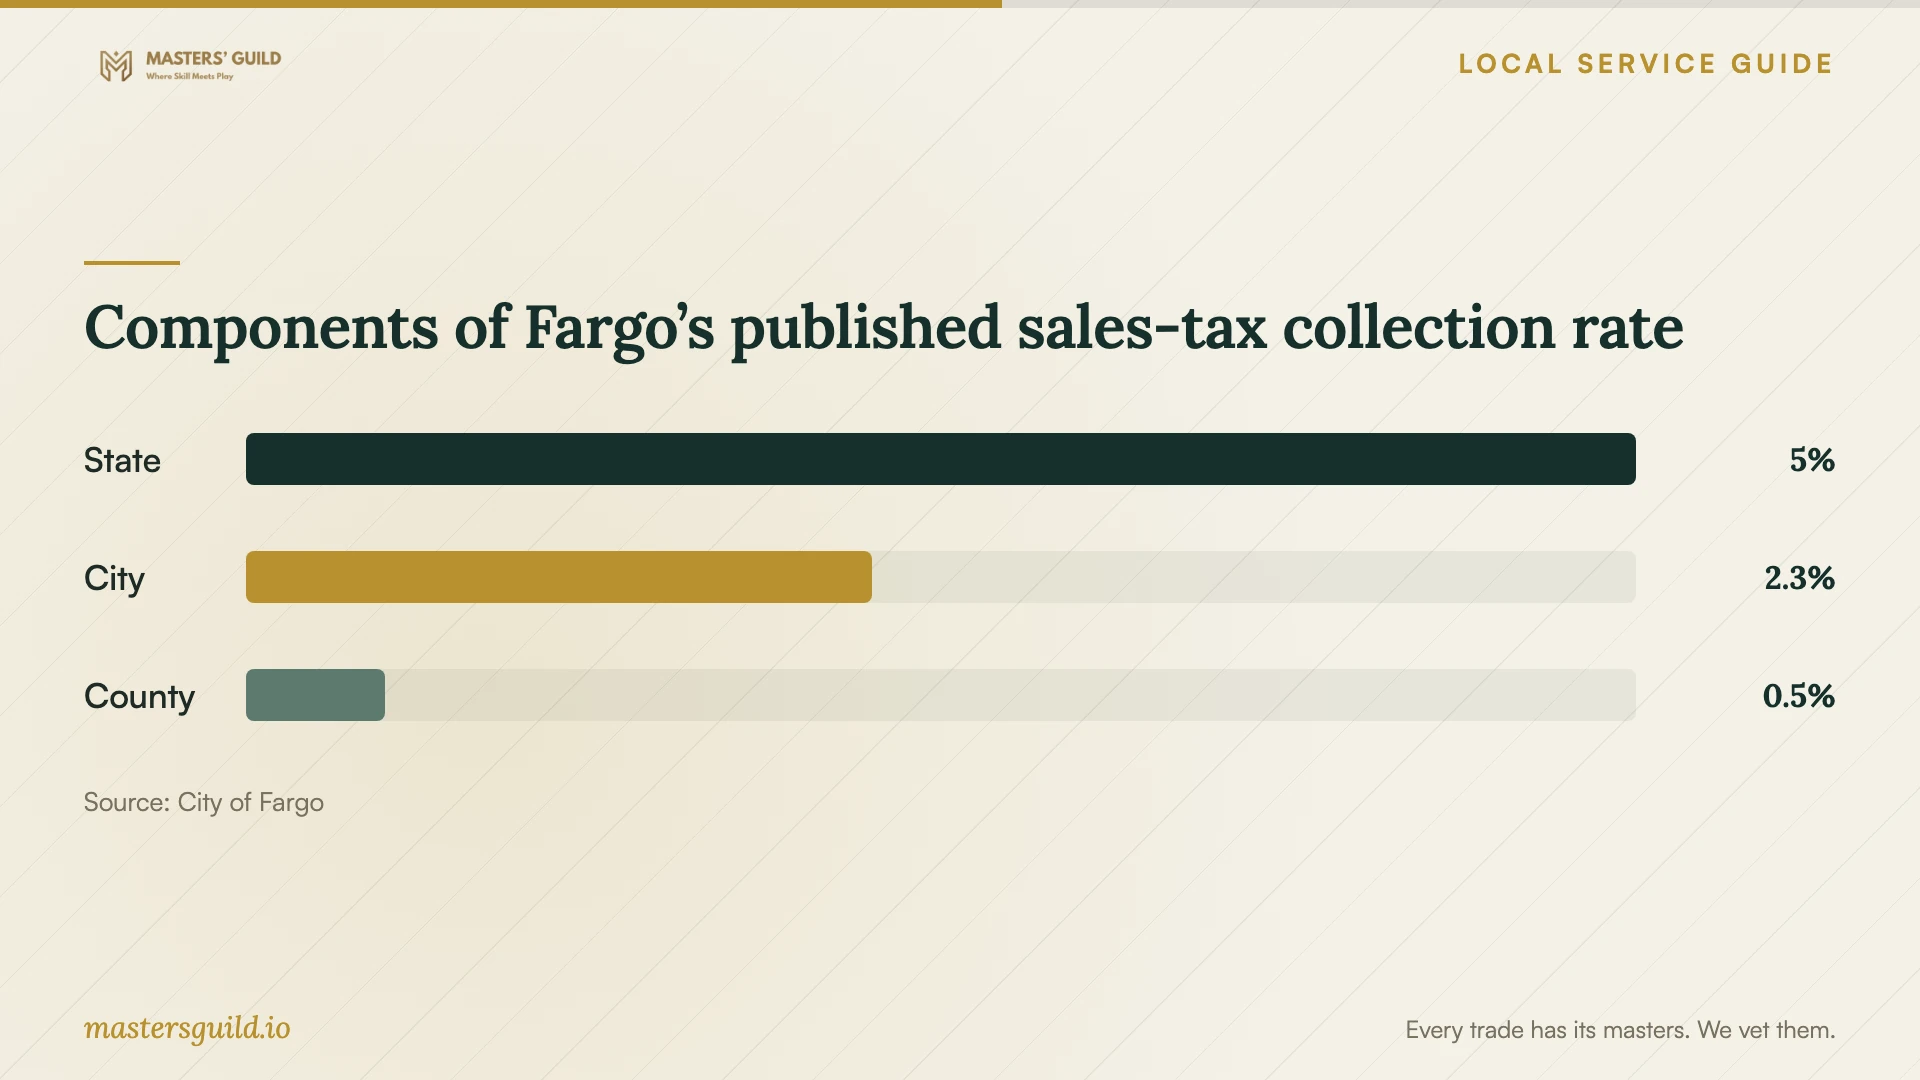
The City of Fargo publishes a sales-tax collection rate of 7.75%: 5% for North Dakota, 2.25% for Fargo, and 0.5% for Cass County. The city identifies the State Tax Commissioner as the sales-tax administration contact. Its FAQ supplies no effective date for those figures. Have your accountant verify the applicable treatment and rate for your transactions before configuring your books. [3]
For your individual return, North Dakota says you may need estimated income-tax payments if you must pay federal estimated income tax and expect North Dakota net tax liability above $1,000. Have your preparer assess both conditions for your personal tax planning. [4]
Create a task list for sales-tax records, payroll information, filing, and payment submission. Assign each task to you or the accountant and decide how you will confirm completion. Keep this list with your engagement documents so you can refer to it during the year.
Prepare records and review your returns
Gather prior returns, income forms, bank and credit-card statements, loan records, payroll reports, asset purchases, and your accounting export. Flag missing information rather than guessing. Arrange a secure transfer method before sharing tax identifiers or account information.
Before authorizing filing, review income totals, owner transactions, state allocations, and balances due with the preparer. Retain your returns and filing confirmations. Record any unresolved accounting issues and decide who will address them.
For your individual federal and North Dakota income-tax returns, North Dakota requires an amended state return within 90 days after you file an amended federal return or within 90 days after the final determination of IRS changes. If a correction affects your individual federal return, discuss the corresponding state amendment with your preparer. [4]
Components of Fargo’s published sales-tax collection rate
Local details that affect your job
Check withholding on Fargo–Moorhead wages
If you reside in North Dakota, qualify for reciprocity, and your employer withheld Minnesota income tax from wages, Minnesota directs you to file Form M1 to recover that withholding. To prevent Minnesota withholding, give your employer Form MWR and renew it each year. Bring wage statements to your appointment so the preparer can assess a refund filing and your next withholding steps. [1]
Include Fargo sales-tax administration in the discussion
Fargo’s published collection rate includes state, city, and Cass County components, and the state administers collection. For taxable sales here, discuss how the accountant will review transaction locations, maintain sales-tax records, and prepare filings. Use the published breakdown as a discussion reference while the accountant verifies the rate applicable to your business. [3]
Choose the work to discuss
| Your situation | Engagement to consider | Bring to the discussion |
|---|---|---|
| Organized records and annual filing needs | Annual preparation | Prior returns and a list of requested filings |
| Unreconciled accounts or missing statements | Record cleanup before preparation | Accounting export and a list of gaps |
| North Dakota residence with Minnesota wages | Reciprocity and withholding review | Wage statements and home-state return information |
| Business activity in Minnesota | Business-income and state-filing assessment | Receipts, activities, and work locations by state |
| Taxable sales in Fargo | Sales-tax accounting and administration | Sales records and transaction locations |
Your hiring checklist
- Describe your entity, ownership, employees, software, and work locations.
- Separate Minnesota wages from business receipts and other income.
- Use the official verification entry point if the candidate offers CPA services.
- Compare proposals using the same records and requested deliverables.
- Assign filing and payment tasks to a named person.
- Gather records and flag missing statements or unexplained balances.
- Agree on document delivery, completion timing, and secure transfer.
- Review returns before authorizing filing and retain confirmations.
Frequently Asked Questions
How should I check a candidate offering CPA services?
Use the North Dakota State Board of Accountancy’s verification entry point to search licensees and firms. Match the names to your proposed engagement, then discuss experience with your business structure and the work you need. [2]
Does reciprocity cover my Minnesota business income?
Minnesota does not provide reciprocity for business income. Its guidance describes a limited exclusion for qualifying compensation from personal or professional services you provide. Give the preparer your activity and income breakdown so they can assess the distinction. [1]
How much should I budget for preparation?
Request comparable written quotes using the same records and requested filings. Include record cleanup and ongoing support in that description. Compare the total proposed fee, exclusions, and conditions for approving additional work.
What should I do after an IRS change to my individual return?
Discuss the North Dakota amendment with your preparer. For individual income-tax returns, North Dakota requires an amended state return within 90 days after filing an amended federal return or within 90 days after the final determination of IRS changes. [4]
Sources and scope
This guide combines the sources below with practical planning guidance. Figures apply to the stated geography and period; request a written quote for your property.