Local service guide
Business tax preparation in Anaheim: hiring help
For business tax preparation in Anaheim, choose a preparer who will confirm your tax classification, define the filings and accounting work you need, and provide a written quote. Verify the individual’s credentials before sharing records. California requires non-exempt paid income-tax preparers to register with CTEC; exemptions include California CPAs, enrolled agents and California State Bar attorneys. Ask who will sign the return and handle questions after filing. [1]
Define the work before requesting quotes
Tell candidates which tax year needs attention, how many owners you have and whether you employ staff, sell products, hold rental property or work across state lines. Include any agency notices. Ask the candidate to explain how they would handle your records and identify the person who will review the work.
For annual preparation, request a list of business returns, owner returns and supporting schedules included in the quote. For recurring accounting, specify account reconciliation, financial reports and the handoff to your tax preparer. Agree on who answers record questions during the year and whether the engagement includes a planning appointment.
For a 2025 LLC return, the FTB booklet distinguishes partnership, corporation and disregarded-entity classifications. Partnership-classified LLCs generally file Form 568, with exceptions such as certain nonregistered foreign LLCs that file Form 565. Qualifying disregarded single-member LLCs also file Form 568. LLCs taxed as general corporations or S corporations use Form 100 or Form 100S. Have the preparer check your elections, circumstances and applicable tax-year instructions; this is not an exhaustive filing guide. [4]
Verify credentials and responsibility
Request the preparer’s full name, credential type and registration or license details. The FTB requires CTEC registration for non-exempt people who charge to prepare or assist with income-tax returns or assume final responsibility for them. Its exempt categories include California CPAs, enrolled agents, California State Bar attorneys and specified banking or trust officials. [1]
CTEC registrants must obtain an IRS Preparer Tax Identification Number, maintain a $5,000 tax preparer bond and renew registration each year. Verify those requirements, then discuss the work you need. Ask who handles corrections, how you can contact that person and what the engagement includes if an agency sends a notice. [1]
For paid preparation of a 2025 Form 568, the FTB instructions require the preparer to sign, provide a PTIN and give the LLC a copy of the return. Arrange a review before submission and request the completed return and filing confirmation. For another tax year, have the preparer confirm the corresponding instructions. [4]
Compare prices for the same deliverables
Request written quotes for the same records and deliverables. Ask whether the provider charges a fixed fee, an hourly amount or a recurring subscription. Identify work that could change the price, and agree on approval before the provider adds services.
For cleanup work, show each candidate the accounts involved, the last reconciled month and missing statements. Define the stopping point, such as reconciled accounts through a named month plus a list of unresolved transactions. Ask whether the quoted return-preparation fee assumes you have completed that cleanup.
Request separate line items for professional charges and government payments. California’s LLC guidance identifies an $800 annual tax and an additional income-based LLC fee, subject to applicable rules and exceptions. Ask the preparer to explain which obligations apply to your entity before you approve the scope. [3] [4]
Build an LLC payment and records plan
Distinguish the first annual-tax payment from later payments. The FTB’s LLC guidance gives a first-year deadline of the 15th day of the fourth month from filing with the Secretary of State. Subsequent annual-tax payments fall on the 15th day of the fourth month of the taxable year. The estimated LLC fee deadline falls on the 15th day of the sixth month of the current taxable year. Ask the preparer to confirm your start date, taxable year, exceptions and exact payment dates. [3]
For tax year 2025, the FTB booklet sets the additional LLC fee threshold at total California annual income of $250,000 or more. The worksheet calculation uses gross income plus applicable cost of goods sold, with California attribution rules and exclusions. Ask the preparer to explain this measure rather than substituting net profit. For a 2026 return or projection, request confirmation against the applicable tax-year guidance. [4]
Gather prior returns, entity documents, election records, payment confirmations and notices. Add bank and credit-card statements, sales reports and records of asset purchases or disposals. Request a secure transfer method and a written list of missing documents. Agree on who schedules payments and who retains confirmations.
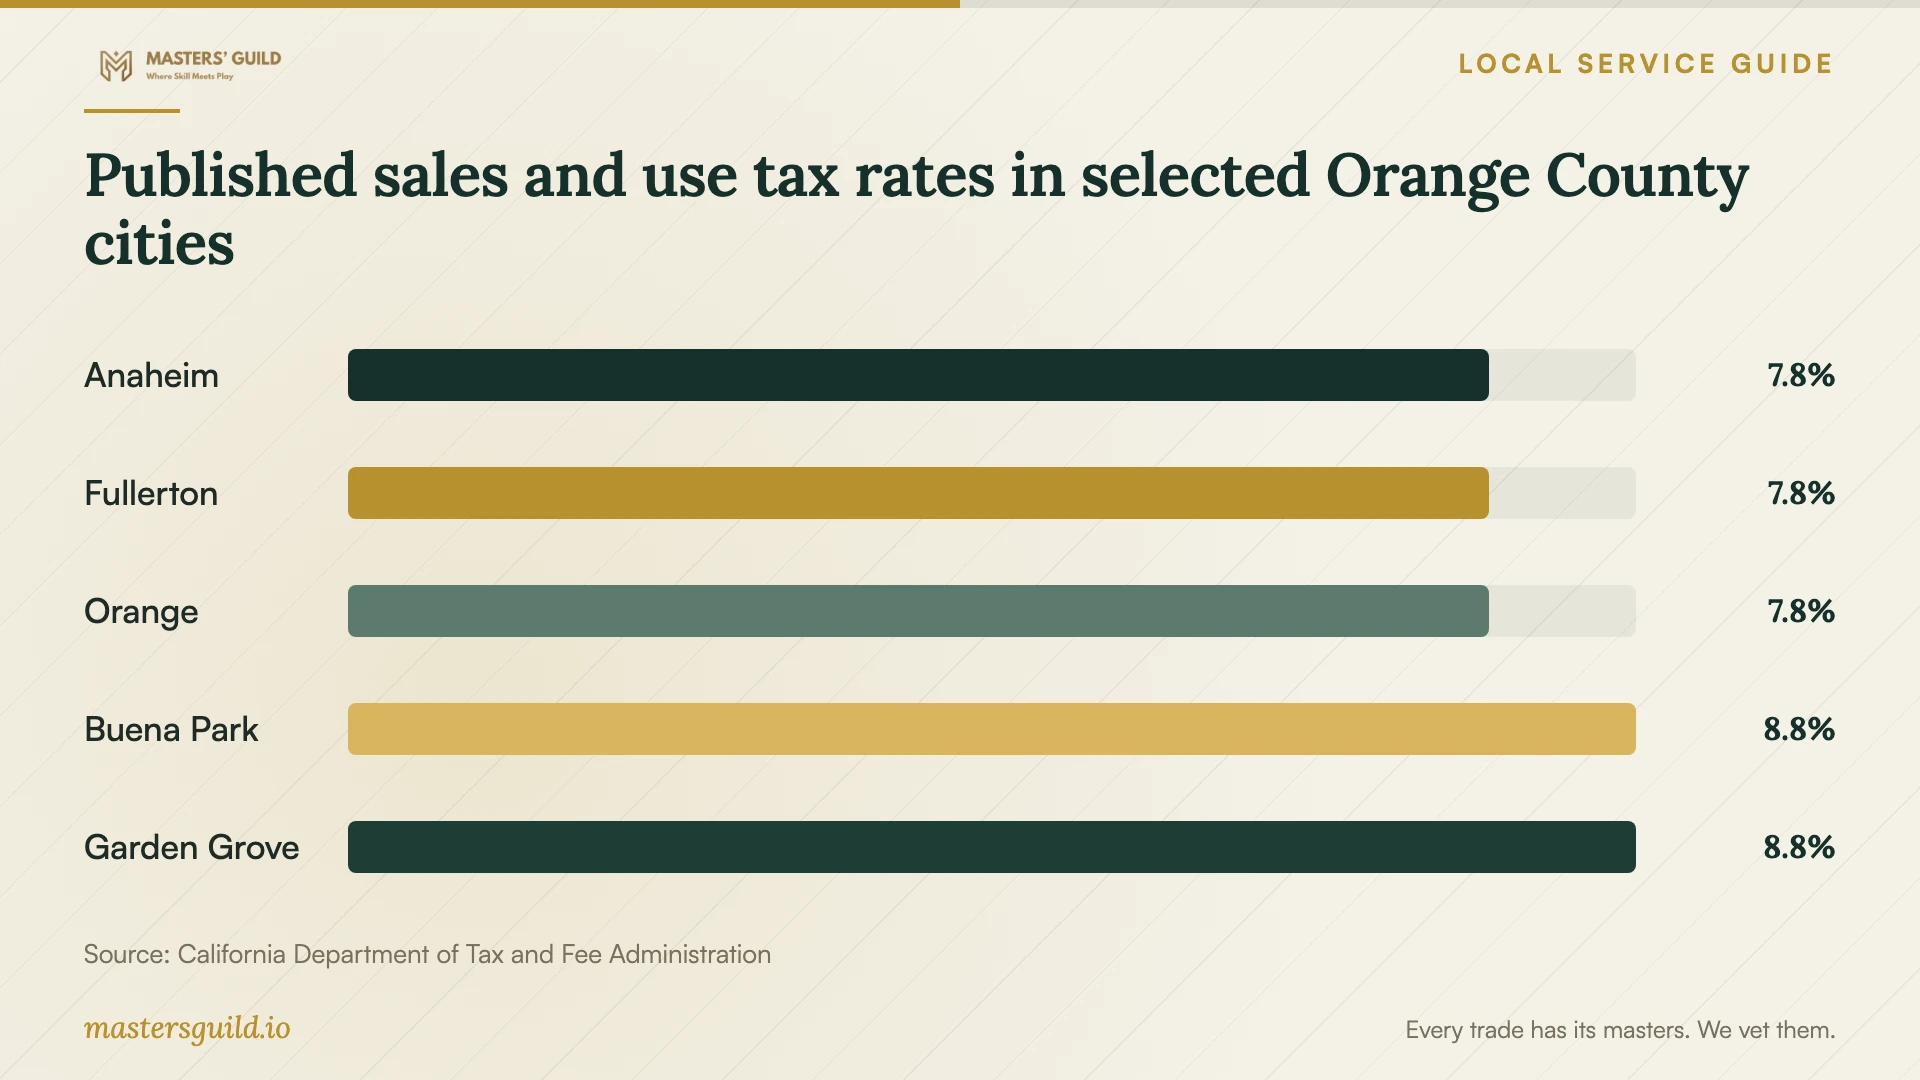
Published sales and use tax rates in selected Orange County cities
Local details that affect your job
Review addresses for Anaheim-area sales-tax work
CDTFA’s table effective October 1, 2026 lists Anaheim, Fullerton and Orange at 7.750%, and Buena Park and Garden Grove at 8.750%. If your business handles transactions involving these locations, include address and transaction review in the accounting proposal. CDTFA provides an address lookup, distinguishes incorporated-city boundaries from unincorporated locations and warns that listed rates may become outdated. Have the accountant confirm the applicable rate and treatment before filing. [2]
Include inactive or closing LLCs in the proposal
California’s statewide LLC obligations apply to qualifying Anaheim businesses. The FTB says the $800 annual tax continues even without business activity until cancellation, subject to exceptions. Its broad first-year exemption covered tax years beginning in 2021 through 2023. For a new, inactive or closing LLC, request a review of payment history, applicable exemptions, final-return work and cancellation paperwork. Include that review in the quote rather than requesting only an owner’s income-tax return. [3] [4]
Choose the scope to request
| Your situation | Work to request | Question before hiring |
|---|---|---|
| Organized records and an annual filing | Return preparation with named deliverables | Which business and owner returns does the quote include? |
| Unreconciled accounts | Bookkeeping cleanup and return preparation | Where does cleanup end, and how will you price unresolved work? |
| LLC classification or elections unclear | Classification and filing-requirement review | Which tax-year instructions and filing exceptions apply to my entity? |
| Transactions involving several city locations | Address-specific sales-tax review | How will you confirm the applicable rate and transaction treatment? |
| LLC stopping operations | Final-return and cancellation review | Which steps must I complete to end future annual-tax obligations? |
Your hiring checklist
- Describe your ownership, entity classification, tax year and requested services.
- Identify the individual who will prepare, review and sign the return.
- Verify the claimed preparer registration or professional exemption.
- Gather prior returns, election records, agency notices and payment confirmations.
- List unreconciled accounts, missing statements and the cleanup period.
- Request separate written prices for cleanup, filings, recurring accounting and follow-up.
- Provide transaction addresses for sales-tax review.
- Agree on document delivery, review dates, payment responsibility and filing confirmations.
Frequently Asked Questions
Must I hire a CPA for business tax preparation?
California permits non-exempt preparers with CTEC registration and specified exempt professionals to prepare paid income-tax returns. Exempt categories include California CPAs, enrolled agents and California State Bar attorneys. Verify the individual’s credential and ask how they would handle your business’s work. [1]
Does every LLC file Form 568?
No. The FTB’s 2025 instructions distinguish tax classifications and filing exceptions. Partnership-classified LLCs generally use Form 568, and qualifying disregarded single-member LLCs also file it. Corporation-classified LLCs use corporation returns; certain other exceptions use Form 565. Have your preparer confirm the requirements for your entity and tax year. [4]
Does an inactive LLC still owe California’s annual tax?
The FTB says the $800 annual LLC tax continues without business activity until cancellation, subject to exceptions. Ask for a review of your status, prior payments and cancellation requirements before assuming that stopping sales ends the obligation. [3] [4]
Can I use Anaheim’s listed sales-tax rate for all transactions?
Have your accountant check the transaction and address. CDTFA’s October 1, 2026 table lists Anaheim at 7.750%, provides address lookup and distinguishes incorporated cities from unincorporated locations. The published city entry alone does not establish the treatment of each transaction. [2]
Sources and scope
This guide combines the sources below with practical planning guidance. Figures apply to the stated geography and period; request a written quote for your property.